The Visa Acquirer Monitoring Program (VAMP) has officially launched – but many are still confused about the new system.
Welcome to your one-stop shop for VAMP information.
VAMP is a Visa program that penalizes both acquirers and merchants for failing to meet certain thresholds related to disputed transactions. It replaces Visa’s former monitoring programs (VDMP and VFMP) and combines them into one rate that monitors fraud and chargebacks for acquirers and merchants.

VAMP is based on Visa’s monitoring of three main metrics:
Merchants will not be included in the program if their total number of TC40s + TC15s is under 1,500 in a calendar month. In the CEMEA region, the floor is much lower: 150 fraud reports and disputes with a combined amount of USD 75,000 or more. Above the floor, the relationship between the three monitored metrics will determine whether a merchant will be enrolled into the program, and subject to penalty fines.
The VAMP ratio is what determines enrollment into the program. Merchants and acquirers whose ratios are above their respective thresholds in a calendar month are at risk of being enrolled.
Here’s how the VAMP ratio is determined:
For a full breakdown of who the April 2026 change affects and how to respond, read Visa VAMP’s tighter threshold is now live: what merchants need to know.
The merchant threshold depends on where the merchant is located. These are the Excessive Merchant thresholds from Visa’s VAMP fact sheet:
Region | Excessive Merchant VAMP ratio | Monthly count of fraud and disputes
|
|---|---|---|
US, Canada, EU, Asia-Pacific | 1.5% (down from 2.2% on April 1, 2026) | 1,500 or more |
Latin America and the Caribbean (LAC) | 1.5% (unchanged since launch) | 1,500 or more |
CEMEA | 2.2% | 150 or more, and USD 75,000 or more |
Acquirer portfolios | Above Standard: 0.5%; Excessive: 0.7% | 1,500 or more (AP, Canada, EU, US); 150 or more and USD 75,000 or more (CEMEA) |
Visa says programs for Brazil, Chile, and India will be announced later. Keep in mind that your acquirer may apply stricter internal thresholds than Visa’s.
The enumeration ratio
VAMP also tracks enumeration: automated card-testing attempts where fraudsters run large numbers of authorizations to find valid card details. Visa defines the VAMP enumeration ratio as enumerated authorization transactions (approved and declined) divided by all authorization transactions (approved and declined).
Visa’s enumeration thresholds are a ratio of 20% and 300,000 enumerated transactions a month at both the merchant and acquirer level. Acquirers must take proactive steps to keep their merchants below them.
Both acquirers and merchants can be subject to fines if they are enrolled into VAMP. Visa’s fees per dispute or fraud report are:
Yes. Visa gives a 3-month (90-day) grace period to merchants and acquirers identified for the first time. It applies if you have not been identified in the previous rolling 12 months. If you breach a threshold again within 12 months, fees are assessed without a new grace period.
Treat the grace period as time to fix the root causes, not as a buffer to rely on.
The advisory period was a grace period for the whole market, allowing merchants and acquirers to better prepare. It ran from April 1 to September 30, 2025. It is now over: fines apply from October 1, 2025, and VAMP is being enforced.
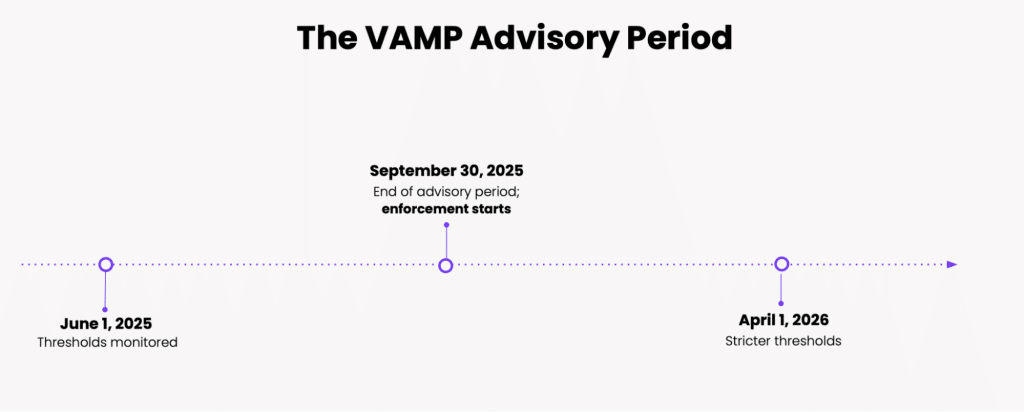
The advisory period is a sort of grace period allowing merchants and acquirers to better prepare. Recently it has been extended until the end of September 2025. Enforcement starts after this date!
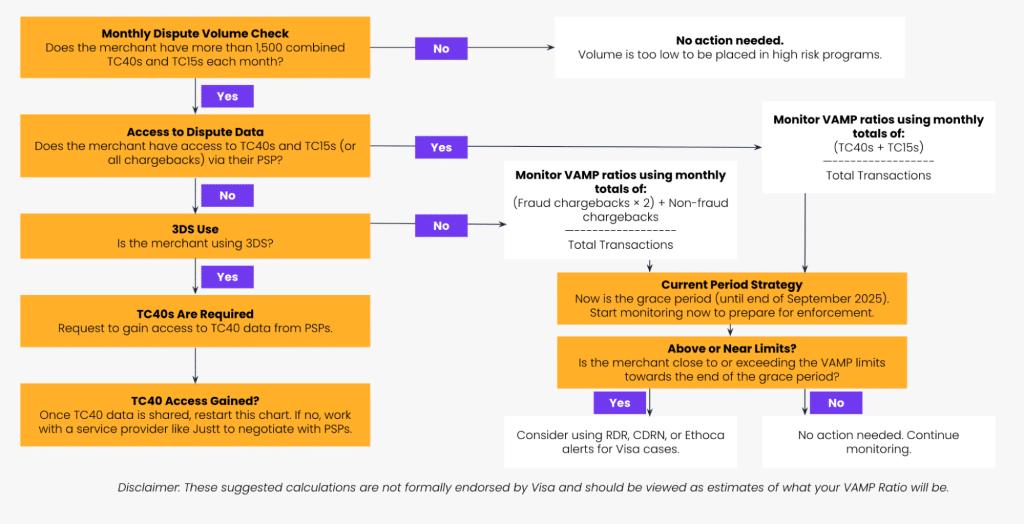
Use this chart to determine if and how you can monitor your VAMP ratio and prepare for enforcement at the end of September 2025.
Before VAMP, Visa ran separate programs for disputes and fraud. On April 1, 2025, Visa retired them and consolidated the earlier VAMP, the Visa Fraud Monitoring Program, and the Visa Dispute Monitoring Program into a single global program.
The biggest change for merchants is that fraud and disputes are no longer judged separately. Under VAMP, both land in a single ratio, much like a combined chargeback ratio, and a fraud report that turns into a fraud chargeback counts twice. A merchant that sat comfortably inside both old programs can still exceed VAMP.
Visa’s new system means merchants must adjust their practices to ensure they remain below excessive thresholds.
Watch Justt Cofounder and Chief Risk office Roenen Ben-Ami explain the 5 key steps merchants should take to prepare for VAMP (or read the summary below).
We’ve abridged our 5 most important preparation tips below- but If you want to explore more expert tips to prepare, check out the full webinar recording or our comprehensive ebook.
In this section:
The advisory period ended on September 30, 2025, and fines now apply. The 1.5% merchant threshold has applied in the US, Canada, EU, and Asia-Pacific since April 1, 2026. If you are identified for the first time, the 3-month grace period is your window to act. Don’t wait for it to start. Use the time now to:
VAMP preparedness starts with understanding where you are, and what you’re up against. This requires a firm understanding of the regulation’s nuances, your TC40 and TC15 rates, and how they measure up under the new system.
Merchants should work with their different payment service providers to ensure access to TC40 and TC15. If the data isn’t readily available, push for commitments on when it will be. Consider this your most critical action item: you can’t manage what you can’t measure.
It’s worth noting that the situation is different for merchants who use 3D Secure (3DS), compared to those who do not:
It might seem like a no-brainer, but the most effective way to prepare for VAMP is to reduce your TC40s and TC15s, even if you’re not currently at risk of enrollment. Aside from ducking VAMP thresholds, this can benefit your entire payments operations.
Merchants can really win by focusing on fraud and disputes. Visa claimed in an online webinar that its data showed that lower risk portfolios have a significantly higher approval rate for their transactions from issuers. Bottom-line, issuers know when merchants have lower fraud and disputes and, therefore, are willing to approve more transactions.
Reducing fraud and chargeback-related disputes is a larger challenge that typically requires a combination of fraud prevention tools, clear return policies, a customer-centric commercial approach, and other operational improvements. An often underused resource in this context is your chargebacks data.
To learn more, read: What Merchants Can Learn from Chargebacks Data
Acquirers face their own stringent thresholds under VAMP: 0.5–0.7% for “above standard” status, and 0.7% for “excessive”. This pressure turns the merchant-acquirer dynamic into a risk partnership where both parties sink or swim together, with potential consequences for businesses facing VAMP enrollment.
Start by asking your acquirer about their own VAMP ratio and how they plan to manage portfolio risk. Learning whether your PSP is comfortably below thresholds or scrambling to improve can inform your negotiation strategy and highlight potential risks to your processing relationships.
It is equally important to review contractual terms that were likely drafted before VAMP existed.
As mentioned above, RDR and CDRNs will allow merchants to avoid TC15s for the purposes of VAMP ratio calculations, as they enable some disputes to be resolved before becoming chargebacks. However, these tools will not cancel out TC40s, as these are registered before a chargeback is filed.
It’s worth noting here that the use of pre-dispute resolution tools can impact your overall revenue recovery rates since they result in refunds that affect your bottom line. Hence, it’s always worth considering your use of them as part of a broader revenue recovery strategy.
Another relevant tool is Compelling Evidence 3.0 (Order Insight), which allows merchants to share transaction data with issuers in real-time. This can help the issuers’ representatives dissuade cardholders from pursuing a dispute (e.g. by clarifying the time and place where the transaction was made based on the data received from merchants). In these cases, both disputes (TC15) and fraud reports (TC40) won’t be filed in the first place, and thus they will be excluded from VAMP ratios.
Struggling to accumulate and analyze the chargeback data needed to prevent TC40s and TC15s? Eager to improve authorization rates and reduce operational costs? Want to preserve and maximize your revenue through this crucial juncture and beyond? Justt has you covered.
Justt’s Insights and Analytics Dashboard doesn’t just consolidate chargeback data across PSPs and acquirers. It analyzes root causes and forecasts revenue retention, enabling targeted interventions that address the root causes of TC40s and TC15s.
With VAMP enforcement now live, merchants have enough to worry about without mounting chargeback losses. Justt’s AI-driven system creates world-leading representments informed by winning strategies across millions of prior cases. This means that your win rates don’t just stabilize, but rise over time.
Without taking the time to learn VAMP’s rules and devise strategies to prevent TC15s and TC40s, merchants may be presented with hefty Visa fines. By fully automating the chargeback process from evidence collection, to submission, Justt handles chargebacks in seconds. This doesn’t just save you revenue, but vital time that you can use to truly understand and prepare for VAMP.
We’ve answered all the specific and general questions we’ve gotten about VAMP over the past few months – check out the full FAQ here, or the highlights below.
No. The drop from 2.2% to 1.5% applies only to merchants in the US, Canada, the EU, and Asia-Pacific. CEMEA region merchants stay at 2.2%, and LAC region merchants were already at 1.5%. Merchants with fewer than 1,500 combined fraud reports and disputes a month are not formally monitored (in CEMEA the floor is 150 and USD 75,000), though your acquirer may still apply its own standards.
Yes. Both the ratio threshold and a minimum of 1,500 combined fraud (TC40) and dispute (TC15) events in a month must be exceeded (150 and USD 75,000 in CEMEA).
By descriptor and acquirer relationship.
VAMP is measured per descriptor per acquirer: Visa identifies a merchant by the static part of its statement descriptor and its acquiring bank.
Yes. Only card-not-present (CNP) settled transactions count toward the denominator in the VAMP ratio calculation.
Only cases that are resolved through CE 3.0 will exclude TC40s, other cases that are resolved though CDRN or RDR will exclude the TC15s, but not the TC40s. Specific TC40 codes have not been publicly listed as being excluded.
Yes, similar to RDR and CDRN, Ethoca Alerts for Visa transactions will exclude TC15s, but not the TC40s if resolved pre-dispute. Checkout.com lists Ethoca alongside CDRN and RDR as tools whose resolved transactions are exempt from the VAMP calculation, and Stripe notes that only Compelling Evidence 3.0 removes a TC40.
Acquirers do not need to receive the RDR and CDRN data in order to calculate VAMP. When RDRs or CDRNs are used properly the TC15 will not come through, so the acquirers or merchant can monitor based off of the TC15s and TC40s that do come in.
While Visa hasn’t issued specific guidelines, it promotes open communication between acquirers and merchants to manage risk effectively.
No changes to 3DS liability protections have been announced as part of VAMP; Visa’s VAMP fact sheet doesn’t mention them. US merchants should note that the separate Visa Secure Excessive Fraud Program still removes liability shift on domestic 3DS transactions until the merchant exits it.